Quick answer: Yes — BSP1 Plumbing works with homeowners insurance claims every week in Orlando, Kissimmee and St. Cloud. We stop the leak, document the cause with photos and a written report, provide an itemized invoice your adjuster can read, and coordinate with your water mitigation company. What we cannot do is promise what your policy will pay: that depends on your carrier and whether the damage was sudden (usually covered) or gradual (usually not).
What “a plumber that works with insurance” really means
Insurance companies do not have “network” plumbers the way health plans have network doctors. Any licensed plumber can do the repair. What matters is that the plumber (1) responds fast enough to limit the damage, (2) documents the failure in the language adjusters use, and (3) separates the plumbing repair from the water damage restoration on the invoice. That is what we do on every claim-related job.
What Florida homeowners policies usually cover
Every policy is different, so read yours or ask your agent — but these patterns hold for most Florida HO-3 policies:
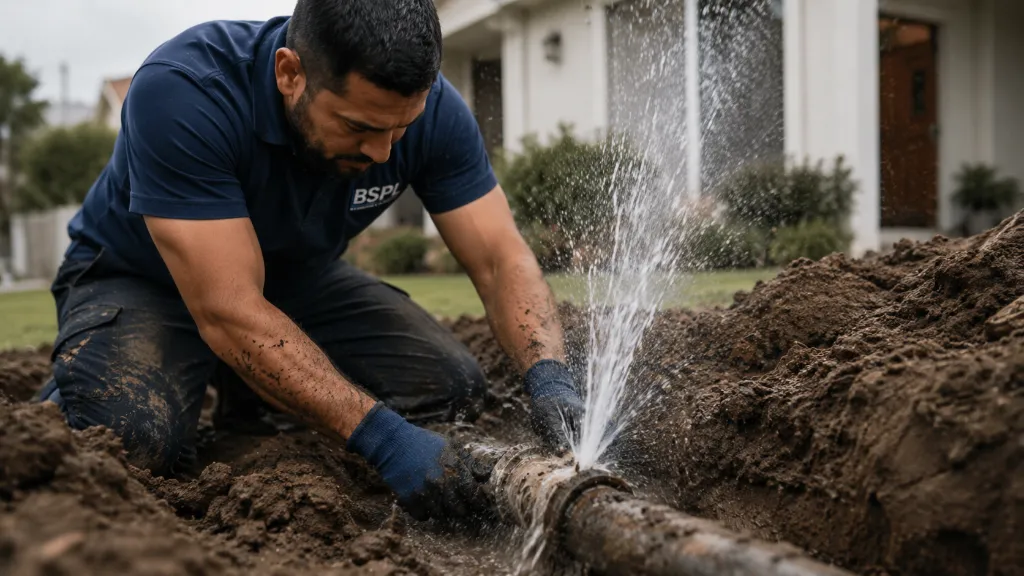
- Usually covered: the resulting water damage from a sudden, accidental event — a burst supply line, a failed water heater tank, a broken washing machine hose, a slab leak that appears suddenly. Tear-out and access to reach the leak is often covered too.
- Usually not covered: the cost of repairing the pipe or appliance itself; damage from a slow leak that went unnoticed for weeks; wear and tear; mold beyond a small limit; sewer backups unless you carry a water backup endorsement.
- Gray area: slab leaks. Many Florida policies cover access (breaking the slab) and the water damage, but limit or exclude the pipe repair. A reroute is sometimes the better path for both the claim and the home.
What your adjuster will ask for
- The date and time the leak was discovered and what was done to stop it
- Photos of the failed component before it is replaced
- The cause of failure in plain terms (corrosion, pressure, age, defect)
- An itemized invoice: diagnosis, access, repair, parts
- Whether the leak was sudden or long-term — this is the deciding question
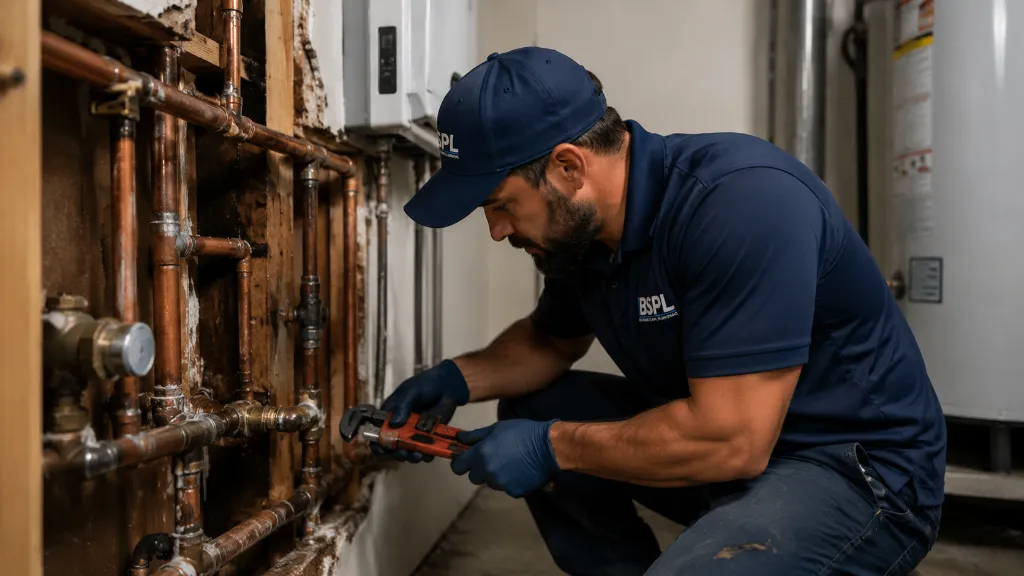
We photograph the failed part, keep it when the adjuster wants to see it, and write the cause of loss on the invoice. If a mitigation company is drying the home, we give them the moisture-affected areas we opened.
The order of operations that protects your claim
- Stop the water first. Main shutoff, then call us. Do not wait for the adjuster to approve the repair — policies require you to prevent further damage.
- Call your carrier the same day to open the claim and get a claim number.
- Get the leak fixed and documented. Keep the failed part.
- Dry-out and rebuild are separate trades; keep their invoices separate from ours.
- Keep every receipt, including emergency service fees and hotel nights if the home was unlivable.
Common Orlando claims we see
Polybutylene and copper pinhole failures in 1970s–1990s homes, water heater tanks letting go in garages and closets, braided supply hoses under sinks and behind toilets, and slab leaks on the hot side in homes with copper under the foundation. If your home still has polybutylene, a repipe is often the best investment you can make — and some carriers require it to renew the policy.
Why Central Florida homeowners call BSP1 Plumbing
We stop the leak fast, document it the way adjusters need, and give you a clean itemized invoice. Licensed, insured and bilingual (CFC1432849), serving Orlando, Kissimmee, St. Cloud and all of Central Florida. Call (321) 732-5615. ★★★★★ Hundreds of 5-star reviews on Google.
Frequently asked questions
Do you bill my insurance company directly?
We invoice you and give you everything the adjuster needs. Most carriers reimburse the homeowner; some mitigation companies accept assignment, but plumbing repair is normally paid by the homeowner and then claimed.
Will insurance pay for the pipe repair itself?
Usually not — most policies cover the resulting water damage and access, not the failed pipe or appliance. Your adjuster makes the final call based on your policy.
Is a slab leak covered in Florida?
Often partially: access and water damage are commonly covered while the pipe repair is limited or excluded. We give you a repair-vs-reroute comparison so you and your adjuster can choose.
Can you give me a report for my claim?
Yes. Every claim-related job gets photos of the failure, the cause of loss in writing and an itemized invoice. Keep the failed part until the adjuster says you can discard it.